Results may vary depending on your particular facts and legal circumstances. The attorney featured above is licensed in Florida. For a full list of attorneys in your state please visit our attorney page.
INSURANCE CLAIM LAWYER IN MIAMI
When an insurance company denies your property damage claim, delays payment, or offers less than you deserve, Morgan & Morgan’s Miami insurance claim lawyers can help fight for the coverage you’re owed.
Results may vary depending on your particular facts and legal circumstances. The attorney featured above is licensed in Florida. For a full list of attorneys in your state please visit our attorney page.



When Your Insurance Company Refuses to Deliver
Insurance is supposed to provide financial protection when the unexpected happens, but policyholders may encounter denied claims, delayed payments, disputed coverage, or settlement offers that fall short of their losses. In Miami, these disputes can put significant financial pressure on families and businesses already dealing with property damage or another major setback.
Insurance claims often turn on complicated policy language, exclusions, deductibles, damage assessments, and questions about how a loss occurred. Resolving a dispute may require reviewing the policy, documenting the damage, examining inspection findings, and challenging an insurer’s interpretation or valuation of the claim.
Contact Morgan & Morgan for a free case evaluation if you are involved in an insurance dispute in Miami. Our attorneys are prepared to review your claim and help you pursue the benefits and coverage available under your policy.
- 700,000+ clients Chose Morgan & Morgan Nationwide.
- $0 upfront Only pay if we win.
- Available 24/7 Get help anytime.
Key Takeaways
Property Damage Claims
Florida Claim Requirements
Denied or Underpaid Claims
Get Legal Help
150,000+ Five Star Reviews
The reasons why clients trust Morgan & Morgan.



Results may vary depending on your particular facts and legal circumstances. Based on select nationwide reviews.
What types of insurance claims can a Miami insurance lawyer handle?
Every policy and loss is different, but insurance disputes can arise from claims involving:
- Hurricane and tropical storm damage
- Wind damage
- Roof damage
- Fire and smoke damage
- Water and plumbing damage
- Mold associated with a covered loss
- Business and commercial property damage
- Theft and vandalism
- Other covered property losses
Coverage depends on the language of the individual insurance policy and the circumstances surrounding the loss. Certain risks may require separate coverage or may be subject to exclusions, deductibles, limitations, or other policy provisions.
That is one reason it can be valuable to have an attorney review the policy itself rather than relying only on an insurer's explanation of the claim.
What if my Florida insurance claim was denied?
A claim denial does not necessarily mean the process is over.
Insurance companies may deny claims for many reasons. An insurer might argue that the cause of the damage is excluded, that the damage resulted from ordinary wear and tear rather than a covered event, that the policyholder did not report the claim on time, or that the amount of damage falls below the applicable deductible.
Sometimes those determinations are supported by the policy. Other times, the policyholder may disagree with the insurer's interpretation or investigation.
An insurance claim attorney can review the denial letter, policy language, estimates, inspection reports, photographs, repair records, and other evidence to determine whether there may be grounds to challenge the insurer's decision.
What if the insurance company underpaid my claim?
Insurance disputes do not always involve a complete denial.
An insurer may acknowledge coverage but disagree about the amount required to repair the property. Disputes can involve the scope of damage, labor and material costs, depreciation, matching issues, replacement costs, or whether particular repairs are related to the covered event.
For a homeowner or business owner facing extensive property damage, the difference between the insurer's estimate and the actual cost of restoring the property can be substantial.
If you believe your insurer undervalued a covered loss, an attorney can review how the claim was evaluated and determine what avenues may be available for challenging the payment.
Are there deadlines for filing property insurance claims in Florida?
Policyholders should act quickly after discovering property damage.
Under current Florida law, initial and reopened property insurance claims generally must be reported to the insurer within one year after the date of loss. Supplemental claims generally must be reported within 18 months after the date of loss.
For weather-related claims involving hurricanes, tornadoes, windstorms, severe rain, and certain other events, Florida law provides rules for determining the date of loss.
Your insurance policy can also impose duties after a loss, including requirements to provide notice, protect the property from additional damage, document the loss, provide requested information, or submit a sworn proof of loss.
Missing an important deadline or failing to comply with policy requirements may affect your claim, so it can be important to seek guidance early.
How long does an insurance company have to handle a property claim in Florida?
Florida law places certain obligations on residential property insurers during the claims process.
In general, an insurer must acknowledge communications concerning a claim within seven calendar days unless an exception applies. After receiving proof-of-loss statements, the insurer generally must begin the reasonably necessary investigation within seven days.
Florida law also generally requires an insurer to pay or deny an initial, reopened, or supplemental property insurance claim, or a portion of the claim, within 60 days after receiving notice, unless statutory circumstances outside the insurer's control prevent it from doing so.
When an insurer denies or partially denies a claim, it generally must provide the policyholder with a written explanation identifying the basis under the policy, facts, or applicable law for its decision.
Insurance claim requirements and insurer obligations can vary based on the circumstances of the claim and applicable Florida law. The information above is general and may not apply to every claim.
What is insurance bad faith in Florida?
Not every disagreement with an insurance company is bad faith. Florida law recognizes certain remedies involving insurers that fail to act in good faith, but bad-faith claims involve specific legal requirements and procedures. For example, Florida law addresses situations in which an insurer fails to attempt in good faith to settle certain claims when it could and should have done so under the circumstances.
Property insurance bad-faith litigation is particularly technical. Florida law generally requires an insured seeking certain extra-contractual damages against a property insurer to first establish through an adverse court adjudication that the insurer breached the insurance contract.
Because the rules surrounding coverage disputes and bad-faith claims have changed over time and depend heavily on the facts of the individual case, policyholders should avoid assuming that a delayed, denied, or underpaid claim automatically establishes bad faith.
An experienced Florida insurance attorney at Morgan & Morgan can evaluate the insurer's conduct and identify the legal remedies that may actually apply.
Meet Miami attorney Joshua Lopez, who has experience handling insurance claims
Morgan & Morgan attorney Joshua Lopez represents homeowners and businesses whose insurance companies have denied, delayed, or underpaid their claims.
A Miami native, Joshua began his legal career defending insurance companies and major cruise lines. That experience gave him firsthand insight into how large corporations and insurers investigate and defend claims. He now uses that experience representing policyholders.
Joshua is admitted to practice in Florida as well as the U.S. District Courts for the Southern, Middle, and Northern Districts of Florida. His practice at Morgan & Morgan focuses on insurance claims.
For Miami policyholders dealing with a difficult insurer, having an attorney who understands both sides of the insurance process can be valuable when determining what comes next.
How can a Miami insurance claim attorney help?
An insurance dispute may require much more than simply sending another letter to the insurance company.
Depending on the circumstances, a Morgan & Morgan insurance attorney may:
- Review your insurance policy and coverage
- Examine the insurer's denial or payment decision
- Review estimates, photographs, reports, and other claim evidence
- Communicate and negotiate with the insurance company
- Determine whether additional documentation could support your claim
- Identify potential violations of Florida insurance law
- Pursue litigation when appropriate
Insurance policies are contracts, and both the language of the policy and Florida law can affect what the insurer is obligated to pay.
What should I do if my insurance claim is denied or underpaid?
Keep as much documentation as possible. Save copies of your insurance policy, claim correspondence, emails, letters, photographs, videos, estimates, invoices, receipts, inspection reports, and records of conversations with the insurer. If the insurance company provides a written explanation for a denial or partial payment, keep that as well.
Avoid making permanent repairs before adequately documenting the damage unless repairs are necessary to prevent additional loss or protect health and safety. Follow the requirements of your policy and keep records of any emergency work you authorize.
Most importantly, pay attention to deadlines. Florida's property insurance laws and your individual policy may impose time limits that affect your rights.
Our Results
How It Works
Unsure what to do next? With 35 years of experience, our personal
injury lawyers will guide you every step of the way.
Contact Us 24/7 - It’s Free
Start your claim
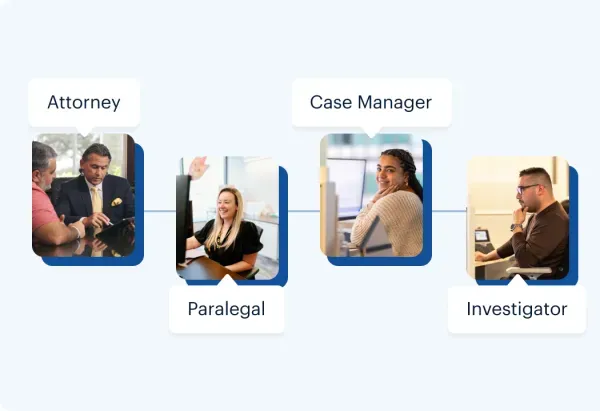
Meet your dedicated attorney
Meet the attorneys
We fight for more
Learn more about the case process
Results may vary depending on your particular facts and legal circumstances. The attorneys shown in these photos may not be licensed in your state. To find an attorney licensed in your area, please visit our attorney page.
Local Care
Backed by America’s Largest Injury Law Firm.
- $35 BillionRecovered for clients
nationwide - 700,000+Clients and families
served - 1,100+Attorneys across
the country - 1Click may change your life
We know your pain.
John Morgan’s brother Tim was injured as a teen. Their experience with a lawyer was a nightmare. John spent 35 years building a firm to do better for families like his. And yours.

The attorney featured above is licensed in Florida. For a full list of attorneys in your state please visit our attorney page.
Results may vary depending on your particular facts and legal circumstances.
Learn More
Injured and not sure what to do next?
We'll guide you through everything you need to know.